Credit Cards in Norway for Foreigners: Requirements and Options
A credit card in Norway for foreigners is available once you hold a Norwegian national ID number (fødselsnummer) and BankID. Many popular cards charge no annual fee and offer an interest-free period of up to 50 days. Below we compare five popular cards, explain eligibility rules, and walk you through the application step by step.
Key takeaways
- All major credit card applications in Norway require BankID, which in turn requires a fødselsnummer (national ID number).
- Norwegian lending rules (utlånsforskriften) cap your total debt at five times your gross annual income.
- Five popular cards — Bank Norwegian, re:member black, Morrow Bank, TF Bank Mastercard, and Instabank — all have 0 kr annual fee.
- Visa and Mastercard are widely accepted across Norway; American Express acceptance is more limited.
- Unsecured consumer credit is registered in Gjeldsregisteret, and banks check it before approving your application.
Providers: credit card norway for foreigners
Free to check. You decide – we show the example and the terms.
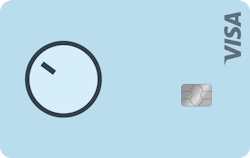 Bank Norwegian-kortet3.4
- Annual fee: 0 kr
- Interest-free period for purchases: Up to 45 days
- You want to choose between cashback and Norwegian CashPoints.
Go to Bank Norwegian-kortetFree and non-bindingRepresentative example: Effective interest rate 24.4 %, 15,000 kr / 12 mnd, 1,849 kr → 16,849 kr
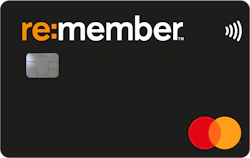 re:member black4.7
- Annual fee: 0 kr
- Interest-free period for purchases: Up to 45 days
- You shop at stores that participate in the discount scheme.
Go to re:member blackFree and non-bindingRepresentative example: Effective interest rate 29.89 %, 15,000 kr / 12 mnd, 1,695 kr → 16,695 kr
 Morrow Bank kredittkort2.2
- Annual fee: 0 kr
- Interest-free period for purchases: Up to 50 days
- You repay purchases in full by the due date.
Go to Morrow Bank kredittkortFree and non-bindingRepresentative example: Effective interest rate 28.77 %, 12,000 kr / 12 mnd, 1,726 kr → 13,726 kr
What Is a Credit Card in Norway for Foreigners?
A credit card in Norway for foreigners works the same way as for Norwegian citizens: the issuer grants you a revolving credit line, and you repay either in full within the interest-free period or in instalments at the stated interest rate. The key difference for newcomers is access — you need a fødselsnummer and BankID before any online application.
A D-number is a temporary ID number issued by Skatteetaten for people not registered as residents. While a D-number lets you open a basic bank account at several banks, most credit card issuers require the full fødselsnummer and BankID for the digital signing process.
Under Norwegian lending rules (utlånsforskriften), your total debt — including credit card limits — may not exceed five times your gross annual income. This applies equally to foreigners and citizens.
Credit Card Norway for Foreigners: Requirements Checklist
You must meet several conditions before a Norwegian bank will approve a credit card. Here is a practical checklist:
- Fødselsnummer — a Norwegian national ID number from Skatteetaten. A D-number alone is usually not enough for credit products.
- BankID — online loan and credit card applications in Norway are signed with BankID. You obtain BankID through your bank once you have a fødselsnummer.
- Registered address — you must be registered in the National Population Register (Folkeregisteret).
- Sufficient income — total debt cannot exceed five times gross annual income. Some cards also set a minimum income (e.g., Instabank oppgir et krav om minst 250 000 kr).
- No negative credit remarks — banks check Gjeldsregisteret, which since 2019 registers all unsecured debt including credit cards and credit lines.
- Minimum age — varies from 18 to 23 depending on the issuer.
If you are new to Norway and do not yet have BankID, you can open a bank account without it at certain banks. DNB, for instance, offers account opening without BankID for a fee of NOK 650. SpareBank 1 Nord-Norge also accepts customers without BankID from age 18 for a fee of NOK 650, requiring a fødselsnummer or D-number.
Compare Credit Cards in Norway for Foreigners (2026)
The table below compares five no-annual-fee credit cards that are popular among newcomers. All data is sourced from the issuers' own websites, last verified October 2026.
| Card | Issuer | Annual Fee | Interest-Free Period | Nominal Rate | Credit Limit | Min. Age | Travel Insurance |
|---|---|---|---|---|---|---|---|
| Bank Norwegian | Bank Norwegian – en filial av NOBA Bank Group | 0 kr | Up to 45 days | 21.99 % | Up to 150 000 kr | 18 | Yes, on conditions |
| re:member black | Entercard Norge, filial av Entercard Group AB | 0 kr | Up to 45 days | 25.22 % | Up to 150 000 kr | 18 | Yes, on conditions |
| Morrow Bank | Morrow Bank AB NUF | 0 kr | Up to 50 days | 24.9 % | Up to 100 000 kr | 20 | Yes, on conditions |
| TF Bank Mastercard | Avarda Bank AB NUF | 0 kr | Up to 43 days | 22.65 % | Up to 200 000 kr | 18 | Yes, on conditions |
| Instabank | Instabank ASA | 0 kr | Not stated | 18.9 % | Up to 100 000 kr | 23 | — |
All five cards charge 0 kr in annual fee and require BankID — making them accessible to any foreigner who has obtained a fødselsnummer and set up BankID through a Norwegian bank.
What Does a Credit Card Actually Cost? Representative Examples
Norwegian credit marketing law requires every provider to show a representative example. Here are the official examples from each issuer so you can compare real costs in kroner:
- Bank Norwegian: Effective rate 24.4 %. 15 000 kr over 12 months. Cost 1 849 kr. Total 16 849 kr.
- re:member black: Effective rate 29.89 %. 15 000 kr over 12 months. Cost 1 695 kr. Total 16 695 kr.
- Morrow Bank: Effective rate 28.77 %. 12 000 kr over 12 months. Cost 1 726 kr. Total 13 726 kr.
- TF Bank Mastercard: Effective rate 26.69 %. 25 000 kr over 12 months. Cost 3 337 kr. Total 28 337 kr.
- Instabank: Effective rate 22.85 %. 45 000 kr over 12 months. Cost 5 219 kr. Total 50 219 kr.
If you pay the full balance within the interest-free period each month, you avoid interest charges entirely. The costs above apply only when you carry a balance.
What Credit Cards Are Accepted in Norway?
Visa and Mastercard are accepted at virtually every shop, restaurant, and online store in Norway. These are the two dominant networks, and all five cards in our comparison run on one of them.
American Express is accepted at some larger retailers, hotels, and airlines — including SAS — but coverage is noticeably thinner than Visa or Mastercard. If you carry only one card, choose Visa or Mastercard for the broadest acceptance.
Norway is widely considered one of the most cashless societies in the world. Contactless payments via card or mobile wallet work almost everywhere, from grocery stores to public transport kiosks. Bringing a foreign Visa or Mastercard will work for short visits, but for daily life as a resident, a Norwegian-issued card avoids foreign-transaction fees and gives you access to local benefits like travel insurance.
How to Apply for a Credit Card in Norway as a Foreigner
The application process is fully digital once you have BankID. Follow these steps:
- Get your fødselsnummer. Register with Skatteetaten when you move to Norway. Processing can take several weeks.
- Open a Norwegian bank account. You can open an account at DNB without BankID (fee NOK 650) or at SpareBank 1 Nord-Norge (fee NOK 650). Bring your passport and fødselsnummer or D-number.
- Activate BankID. Once your bank account is open and you have a fødselsnummer, the bank will help you set up BankID — either on your phone (BankID på mobil) or via a code device.
- Choose a credit card. Compare cards using the table above. Consider the interest-free period, nominal rate, credit limit, and whether travel insurance matters to you.
- Apply online. Visit the issuer's website, fill in the application, and sign with BankID. The bank checks Gjeldsregisteret and your income automatically.
- Receive your card. If approved, the physical card arrives by post.
Remember: under Norwegian lending rules, unsecured consumer loans (including credit card debt) normally have a maximum repayment period of 5 years unless used for refinancing.
Which Credit Card in Norway Is Best for Foreigners?
The best card depends on how you plan to use it. Here is a quick decision guide:
Best for Travel Insurance
TF Bank Mastercard includes travel insurance on conditions and offers the highest credit limit among the five cards — up to 200 000 kr. The nominal purchase rate is 22.65 %. Minimum age is 18.
Best Interest-Free Period
Morrow Bank kredittkort gives you up to 50 days interest-free — the longest in this comparison. The trade-off is a slightly higher nominal rate of 24.9 % and a minimum age of 20.
Lowest Nominal Rate
Instabank kredittkort has the lowest nominal purchase rate at 18.9 %, but requires a minimum age of 23 and Instabank oppgir et krav om minsteinntekt på 250 000 kr. No interest-free period is stated by the issuer.
All-Round Pick
Bank Norwegian combines a 45-day interest-free period, travel insurance on conditions, and a competitive nominal rate of 21.99 %. The credit limit goes up to 150 000 kr, and the minimum age is 18.
High Credit Limit with Insurance
re:member black also offers up to 150 000 kr and travel insurance on conditions. The nominal rate is 25.22 %, so it suits cardholders who pay in full each month and value the insurance benefit.
Practical Tips for Newcomers Using Credit in Norway
Managing credit wisely is especially important when you are building a financial life in a new country. Here are tips tailored to foreigners:
- Pay the full balance each month. This way you benefit from the interest-free period and pay zero interest.
- Monitor your debt. Gjeldsregisteret (gjeldsregisteret.com) has registered all unsecured debt since 2019. Banks check it, and high existing debt reduces your chances of approval.
- Respect the 5× income rule. Norwegian lending rules cap total debt at five times gross annual income. Plan your credit card limit accordingly.
- Use free help if you struggle. NAV økonomi- og gjeldsveiledning offers free financial counselling. Call 55 55 33 39.
- Keep your Folkeregisteret address current. Your card and bank correspondence arrive by post. An outdated address can cause missed statements and fees.
Questions and answers: credit card norway for foreigners
Can you get a credit card as a foreigner?
Yes, foreigners living in Norway can get a credit card once they have a fødselsnummer (Norwegian national ID number) and BankID. A D-number alone is typically not sufficient for credit products. You must also meet income and debt requirements under Norwegian lending rules.
Which bank is best for foreigners in Norway?
Several banks allow account opening without BankID, which is helpful for newcomers. For example, DNB charges NOK 650 and SpareBank 1 Nord-Norge also charges NOK 650. Other SpareBank 1 branches and OBOS-banken also offer options for customers without BankID. Once you have a bank account and BankID, you can apply for credit cards from any issuer.
How to get a credit card in Norway?
First obtain a fødselsnummer from Skatteetaten, then open a bank account and activate BankID. Apply online at the card issuer's website and sign with BankID. The bank checks Gjeldsregisteret and your income before approving. The card is delivered by post after approval.
How to get a Norwegian credit card?
You apply digitally on the issuer's website and sign with BankID. Requirements include a fødselsnummer, sufficient income (total debt may not exceed five times gross annual income), and no negative credit remarks. All five cards in our comparison — Bank Norwegian, re:member black, Morrow Bank, TF Bank Mastercard, and Instabank — require BankID.
What credit cards are accepted in Norway?
Visa and Mastercard are accepted almost everywhere in Norway, including shops, restaurants, and online stores. American Express has more limited acceptance, mainly at larger retailers and hotels. For daily use, a Visa or Mastercard is the safest choice.
Is the Norwegian credit card worth it?
A Norwegian credit card with 0 kr annual fee and travel insurance can be very worthwhile if you pay the balance in full each month. You avoid interest charges entirely and benefit from the insurance. Carrying a balance, however, means paying nominal rates between 18.9 % and 25.22 % depending on the card.
See which no-fee credit card fits your needs — updated for October 2026.
Compare Cards Now – Bank Norwegian-kortetSources
- Bank Norwegian – credit card
- re:member black – Entercard
- Morrow Bank – credit card
- TF Bank Mastercard – Avarda Bank
- Instabank – credit card
- DNB – become a customer without BankID
- SpareBank 1 Nord-Norge – become a customer without BankID
- Gjeldsregisteret
- Skatteetaten – D-number
- NAV – økonomi- og gjeldsveiledning
Advertiser content: SmartMoney may earn a commission when you continue via buttons marked "Ad". It costs you nothing extra, and the order is not a ranking.